I Earn £150,000 a Year. I Spent Twelve Months Auditing Our £10 Secret Santa. HR Called an Emergency Meeting When I Found the Duplicate.
A senior operations director says a duplicate name in the office Secret Santa allocation left one colleague with two gifts and another with none.
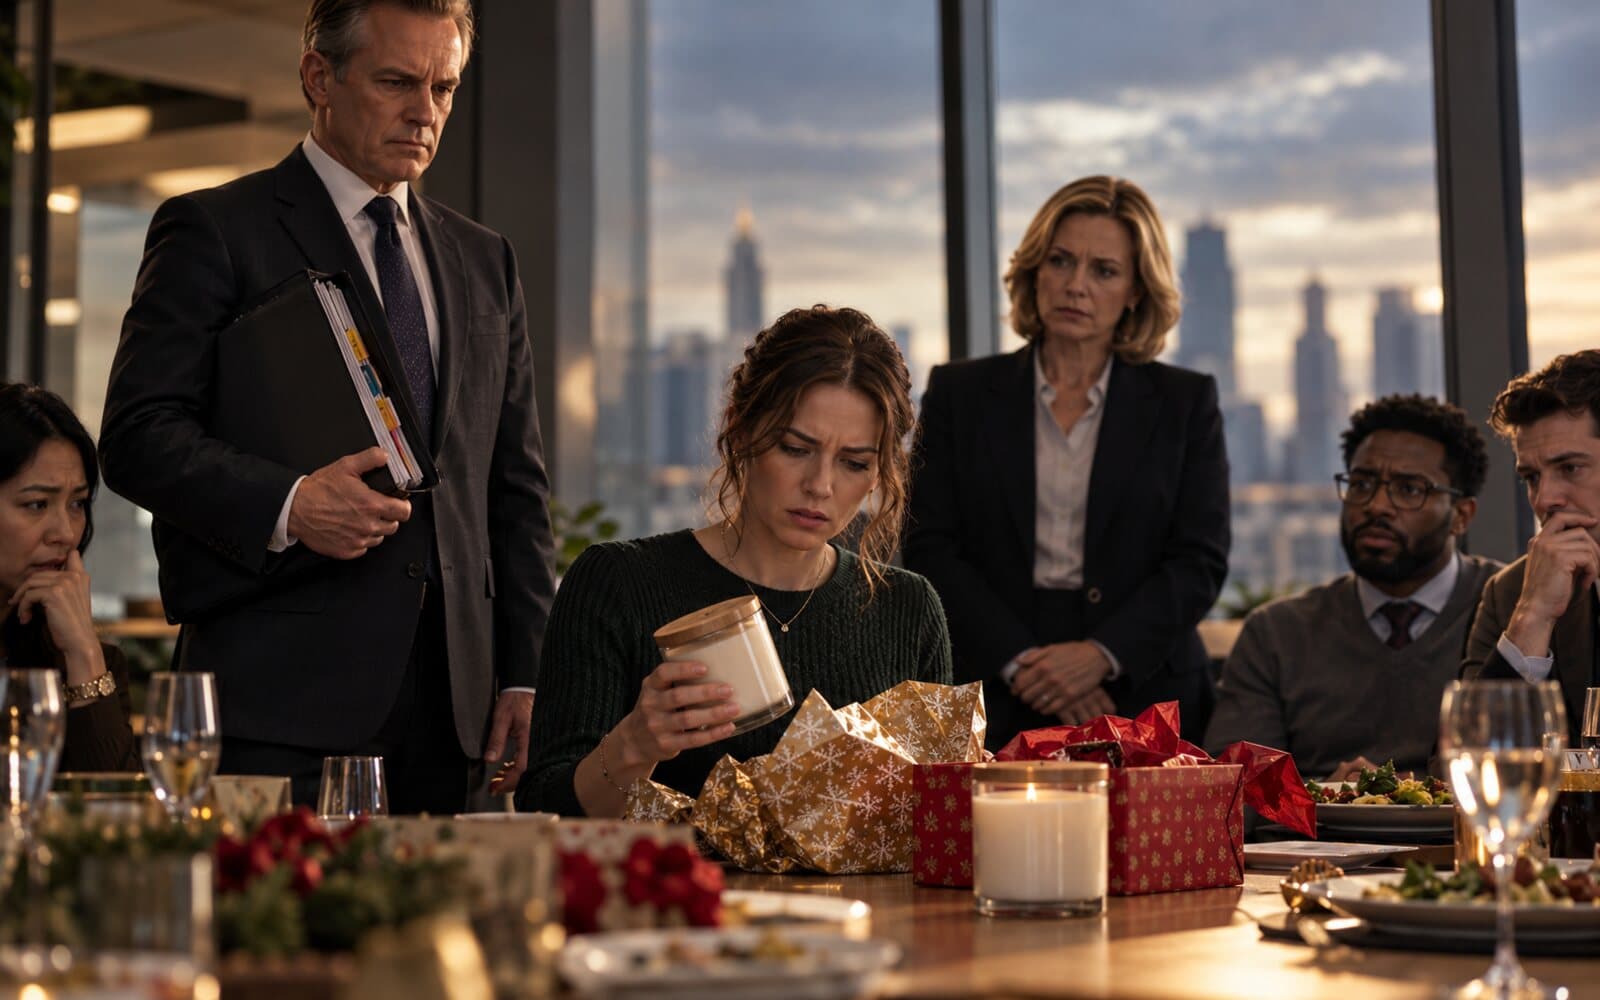
News Intro
I earn £150,000 a year as a director of operations. I have negotiated supplier agreements, overseen restructures, and presented risk reports to people who decide whether entire departments continue to exist.
For twelve months, I have also maintained a private record of discrepancies in our office Secret Santa allocation.
The file has 23 tabs.
On Tuesday, HR scheduled an emergency meeting.
On Wednesday, I placed the allocation record on the table and asked one question.
“Who received the second gift?”
Nobody answered.
The office Secret Santa has a £10 limit. It is written in the invitation, repeated in the calendar reminder, and printed on the card beside the paper slips. The limit exists so that participation remains straightforward and nobody feels obliged to turn a small office custom into a display of personal means.
That was the stated purpose.
The process itself had never been straightforward.
The First Allocation
Twelve months earlier, on 3 December 2024, our office held its annual Secret Santa exchange. I watched Paula from payroll open a second parcel. Another colleague reached the end of the exchange without receiving a gift.
“Apparently the list has chosen for me,” she said.
People laughed. The exchange moved on.
One person had received two gifts. One person had received none.
I asked Martin in HR whether the allocation record had been checked. He said the slips had been drawn from a bowl and the process was informal.
“That’s how Secret Santa works,” he said.
I asked how an informal process had produced a duplicate recipient.
He shrugged and moved the empty gift bag from the chair beside him.
I did not raise it again in the room. I had been a director long enough to know that a question dismissed in public was often more useful when supported by a record.
At 4:16 that afternoon, I opened a spreadsheet and began the record.
I named it Allocation Review.
The first tab listed the eligible employees. The second recorded who had confirmed participation. The third showed the date invitations went out. By the end of the week, there were six tabs. By the end of January 2025, there were nine.
I kept the file private because I did not want the people involved to feel watched. I wanted the process to be understood before anyone was asked to explain it.
Over the next twelve months, I recorded each change that could affect the allocation: new starters, leavers, people on extended leave, invitations sent after the deadline, and names added to the bowl after the original count. I noted which version of the participant list had been printed and when. I retained the calendar notices and saved the messages in which staff confirmed or withdrew.
By September 2025, I had 17 tabs.
By November 2025, I had 21.
The twenty-third tab was called Reconciliation.
It contained one row for each participant, a column for the person they had drawn, a column for the person who had drawn them, and a count that should have equalled one in both directions.
I used conditional formatting. A duplicate turned amber. A missing assignment turned red.
There was no reason for anyone else to know about the file. The office had a system, and I was checking that the system worked.
The List
This year, I offered to oversee the draw after Martin said he was too busy to manage it alongside the annual leave schedule. I did not tell him about my spreadsheet. I told him I had a clear hour before a supplier review.
On 3 December 2025, at 10:00, we gathered in the smaller conference room. There were 22 participants on the final sign-up list, including me. Martin brought the HR export he had downloaded on 27 November and printed that morning.
Before he cut the slips, I compared each row against the final sign-up list.
The totals matched. The names did not.
Paula appeared twice in the export. Nadia, who had confirmed her participation on 28 November, did not appear at all. The export had 22 rows, but only 21 distinct participating employees.
I put my pen down.
“We need to stop here. Paula is listed twice and Nadia is missing.”
Martin looked at the two pages.
“There are 22 rows.”
“There are 22 participants. There are only 21 distinct participants on this export.”
“The system has everyone in it.”
“It has Paula twice. It does not have Nadia.”
I showed him Nadia’s confirmation message. It was dated 28 November and had the same response status as every other participant.
“We can print a new list,” I said. “We should not draw from this one.”
Martin set the pages down.
“It’s a bowl of names, not a payroll run.”
“The duplicate will give one person two assignments and leave another without one.”
“That won’t happen. We have 22 slips.”
The number of slips did not resolve the names on them. I said so. I asked him to pause while HR corrected the export.
Martin cut the slips himself.
I wrote down the time: 10:07. I also wrote that I had advised against proceeding and had not certified the participant list. Martin placed the slips in the white ceramic bowl and told everyone the draw could begin.
We agreed nobody could draw their own name. If they did, they would return it and draw again. I took my slip with the others. I did not handle the bowl or verify the stack.
The draw took eleven minutes.
At 10:18, Martin gathered the signed draw sheets and put them in his notebook. He said he would transcribe the assignments later.
I entered the assignments from the signed draw sheets into Tab 23. I compared the giver column with the recipient column. I checked it once from top to bottom and once from bottom to top.
The amber cell appeared beside Paula’s name. The red cell appeared beside Nadia’s.
The export had produced exactly the discrepancy I had identified before the slips were cut: Paula had been assigned twice. Nadia had no giver.
I printed the reconciliation and placed it in a locked drawer.
At 10:46, Martin sent a message to the group.
All allocations are confirmed. Please bring your gifts to the Thursday lunch. £10 maximum.
I saved a copy.
Over the following week, colleagues began leaving gifts in the storage room. I saw one small parcel with Paula’s name on it. I saw another with the same name, in the same handwriting, beneath it.
I took a photograph of the labels from the doorway and recorded the time. I did not open the parcels. I had no authority to inspect the contents, and the allocation question concerned the names, not the gifts themselves.
On Monday, 8 December, I asked Martin to confirm whether he had retained the signed draw sheets.
“They’re with the invitations,” he said.
“Which version of the participant list did you use?”
“The final one.”
“The file has three versions marked final.”
He sighed. “I used the one I printed.”
“When did you print it?”
“I don’t remember.”
I added the exchange to my notes. In the spreadsheet, I created Tab 22: Source Documents. Tab 23 remained the reconciliation. The sequence mattered. A conclusion without its source was an opinion.
At 4:12 that afternoon, Martin sent another message.
Reminder: Thursday lunch is at 12:30. If you drew someone who has since left, please speak to me privately.
The message contained no reference to the duplicate. I saved it beside the earlier confirmation.
On Tuesday, 9 December, I walked past the storage room. The two parcels with Paula’s name were still there. A third parcel had appeared beneath them, addressed to Martin.
I did not photograph that one. It was not relevant to the allocation discrepancy.
At 8:17, I sent Martin a calendar invitation for a ten-minute check-in. He declined it with the note, Can we deal with this after the lunch?
I replied, The allocation is the reason for the lunch. We should establish the record before gifts are distributed.
He did not respond.
The Emergency Review
At 9:03, I sent the same message to Helen in HR, attaching the participant list, the signed draw sheets, and a one-page summary of the duplicate and missing assignment. I did not attach all 23 tabs. I wanted the question to be visible without burying it in the full file.
At 9:26, Helen called me.
“I’ve seen your summary,” she said. “Why have you been tracking this since 3 December last year?”
“Because at the 3 December exchange, one person received two gifts and one person received none.”
“You’re saying it happened again?”
“The allocation count shows a duplicate and a missing recipient.”
“And you have records?”
“Twelve months of them.”
There was a pause.
“I think we need to discuss this in person.”
The Meeting
At 10:02 on Tuesday, 9 December, HR sent a calendar invitation titled Secret Santa Allocation — Emergency Review. The meeting was set for Wednesday, 10 December, at 9:30. It included Helen, Martin, the office manager, and me.
I accepted.
That evening, I checked all 23 tabs against the original messages and timestamps, compared the signed sheets with Martin’s list, and prepared three copies of the reconciliation.
One for HR.
One for the office manager.
And one for the record.
I had learned long ago that accountability begins when someone asks why there are three copies.
The Second Gift
At 8:00 on Wednesday, 10 December, I placed the file in a grey document case and took it to the office.
The Secret Santa lunch was due to begin at 12:30 on Thursday, 11 December.
The emergency meeting began at 9:30.
Helen sat at the head of the table. Martin sat to her right. The office manager, Priya, brought a notepad and a paper cup of tea. I placed the grey case in front of my chair but did not open it.
Helen began.
“We’re here because there’s a concern about the allocation process.”
“It’s not a concern,” I said. “It’s a discrepancy.”
Martin shifted in his chair.
Helen looked at me. “Can you explain what you found?”
I opened the case and removed the one-page summary.
“Twenty-two employees participated. There were 22 slips in the bowl, but the HR export contained only 21 distinct participating names. The signed draw sheets show that one recipient appears twice and one recipient does not appear at all.”
Martin said, “The export came from HR. It’s the version the system produced.”
“A mistake is still a result.”
“Nobody’s been harmed.”
I kept my hands flat on the table.
“The person with no giver has been excluded from a process they agreed to join. The person assigned twice may receive two gifts while another receives none. That is the allocation.”
Priya stopped writing.
Helen asked, “Do we know who received the duplicate assignment?”
“Yes.”
“Who?”
“I want to establish the source first.”
I passed the signed draw sheets around the table. Then I placed the HR export beside the final sign-up list. The sheets had each been initialled by the person who drew. The printout had been made at 9:58 on 3 December from the roster Martin downloaded on 27 November. I had identified the duplicate and omission before he cut the slips.
Martin leaned forward.
“You can’t tell from those sheets. People wrote names differently.”
“The initials are consistent with the confirmations in the group messages.”
“You’ve been saving our messages?”
“I retained the messages relevant to the allocation.”
Helen looked at the grey case.
“What’s in there?”
“The source records. Twenty-three tabs. The summary is on top.”
Martin gave a short laugh.
“Twenty-three tabs for Secret Santa?”
I looked at him.
“Twenty-three tabs for the allocation record.”
The room went still.
Helen asked me to continue.
I showed them the list of participants, the two duplicate assignments, and the missing recipient. Then I placed the HR export used to print the slips beside the final sign-up list. The export had 22 rows, but Paula appeared twice and Nadia did not appear at all. Nadia was on the final sign-up list. The export had been created before her participation was added and had retained a duplicate Paula record. I showed them Martin’s message declaring the allocations confirmed seven minutes after the draw sheets had been put away.
I asked whether he had corrected the export after I identified the duplicate and omission.
“No,” he said.
“Did you pause the draw?”
“No.”
“Did you compare the givers with the recipients before confirming the allocation?”
He looked at Helen.
“No,” he said.
I turned to the reconciliation page.
“The record now establishes that one person was selected twice.”
Helen folded her hands. “Can we identify them?”
“Yes.”
“And the person without a giver?”
“Yes.”
Martin stared at the signed sheets. His face had gone pale around the mouth.
Helen said, “Before we name anyone, we need to know what has already been distributed.”
“The gifts are due at lunch,” I said. “The distribution has not occurred.”
“Has anyone brought a gift in early?”
“Two parcels are in the storage room with the duplicate recipient’s name.”
Martin stood up.
“I’ll check.”
“Please don’t move them,” I said.
He stopped.
For twelve months, I had watched this process move forward on the assumption that the paperwork would somehow correct itself. Now the original record was on the table. Every person in the room could see the duplicate. Nobody had to rely on a memory of the bowl or a claim about who had drawn which folded slip.
Helen asked Priya to bring the two parcels to the meeting room.
At 10:14, she returned with both gifts. They were wrapped in matching cream paper. Each had a handwritten tag bearing the same name.
The name was Paula’s.
Martin sat down again.
“So Paula has two gifts,” Priya said.
“The allocation record assigns her two givers,” I replied. “We have not yet established what the gifts are.”
Helen looked at the tags. “The £10 limit is per gift, correct?”
“That’s what the invitation says.”
“Then the total value could exceed the limit.”
“The limit applies to what each participant spends. The recipient allocation is a separate issue.”
“We need to establish the value before we distribute anything.”
I agreed.
Helen asked Martin to contact the two assigned givers separately. He did. The first replied within four minutes. The second was in a meeting and did not respond.
At 10:37, Martin said the first gift was a scented candle. He had not opened it; the giver had told him when he asked whether the package could be identified.
At 10:49, the second giver replied that their gift was also a scented candle.
Nobody moved.
Helen looked at the two matching parcels. Priya kept her pen above the notepad. Martin stared at the duplicate assignment on the page.
I turned to Tab 23.
“The final allocation was not checked,” I said. “The duplicate recipient was not caught before gifts were purchased. The person with no giver remains unassigned.”
“We can fix this before lunch,” Helen said.
“We can correct the allocation,” I replied. “We cannot undo the draw.”
Helen asked whether there was a way to account for the unassigned colleague before lunch.
There was a way to account for the unassigned colleague without altering the gifts already purchased for Paula. Helen could issue a £10 gift card from the office budget and keep the original allocation with the record. It would not erase the duplicate from the signed sheets.
At 11:06, Helen made the decision. The two gifts had already been purchased for Paula, and the givers had followed the names they were given. She would not transfer either gift without their agreement. The colleague with no assigned giver would receive a £10 gift card from the office budget, and next year's process would have two independent checks before the allocation was confirmed. The original sheets would remain with the record.
At 12:30 on Thursday, 11 December, the lunch began.
The colleague without an assigned giver received the £10 card from Helen. Paula opened the first parcel, then the second. Both gifts were scented candles.
The room became quiet as Paula looked from one candle to the other. The duplicate was no longer a red cell in Tab 23. It was sitting in front of everyone.
At 12:42, Martin came over to my desk.
“You could have told me you were keeping a spreadsheet,” he said.
“I raised the discrepancy last year.”
“You could have reminded me.”
“I did. I asked you to verify the list on Monday.”
He looked at the pile of documents in the grey case.
“You’ve made this very formal.”
“The allocation was formal enough to exclude someone.”
He left without replying.
The next morning, Helen sent an updated process note. The participant list would be frozen three days before the draw. Two people would independently verify the slips. The final allocation would be checked in both directions before the invitation was marked confirmed.
I saved the email to Tab 22.
On Friday, Paula stopped by my office. Both scented candles stood on the corner of her desk, beside the plant she had kept alive through two office moves.
“I heard there was a mix-up,” she said.
“The record was corrected. The gifts had already been distributed.”
“I got two candles.”
“Both tags had your name.”
She looked at the candles, then back at me.
“Both were scented. One is vanilla, the other is cedar.”
“The allocation showed you twice.”
She was quiet for a moment.
“I suppose at least they chose different scents.”
“That does not alter the record.”
She thanked me and went back to payroll.
I reopened the spreadsheet. The original allocation remained preserved. A separate note recorded HR’s response and the gift-card remedy.
There were still 23 tabs.
At the bottom of the final sheet, I added the date of the correction and the name of the person who verified it.
Then I closed the file.
For twelve months, I had kept a record of what happens when responsibility is treated as an assumption. This year, the missing participant was identified, the duplicate assignment documented, and a remedy recorded. Next year's process would use a verified participant export and two independent checks before the invitation was marked confirmed.
Paula had received two scented candles.
The record made the reason impossible to forget.
Topics